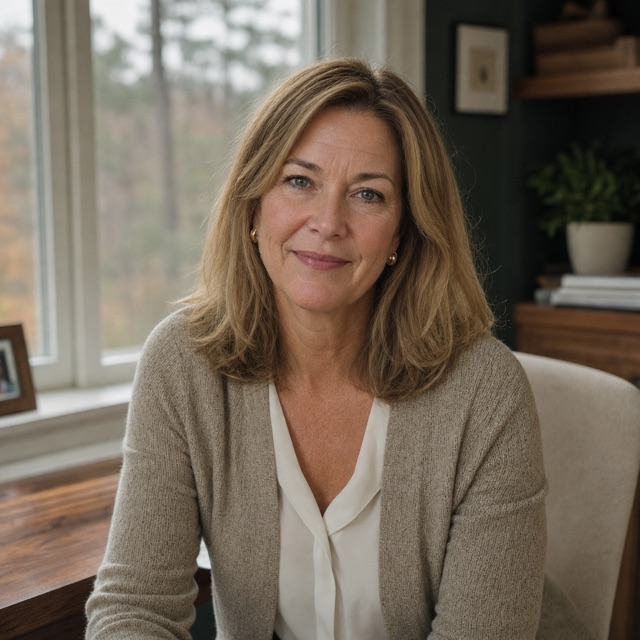
Nell
Nell Varden, CFP®
Founder and planner
Opened Varden in 2015 after twelve years at an Atlanta firm. Her father flew for thirty-one years.
Fictional person
Planning for the day the airline takes you off the schedule, and for the years at home after it. From Peachtree City, Georgia.
The decisions at 65
The election packet arrives with a deadline, the paycheck has an end date, and the choices can't easily be undone. These are the questions pilots bring to the first call.
It depends on three things, and the first is how much income a surviving spouse would need on their own. We work through all three with the plan documents in front of us before anything is signed.
The answer is usually different for each spouse. We look at both records together, because one choice changes what the other would receive later.
The written plan answers this year by year: which accounts pay for which years, and what changes if markets or plans do.
Pilots move more than they remember. Teo starts with where you lived each year and files in every state you owe tax.
Every plan we write answers this on one page, in plain numbers, so both of you know the answer.
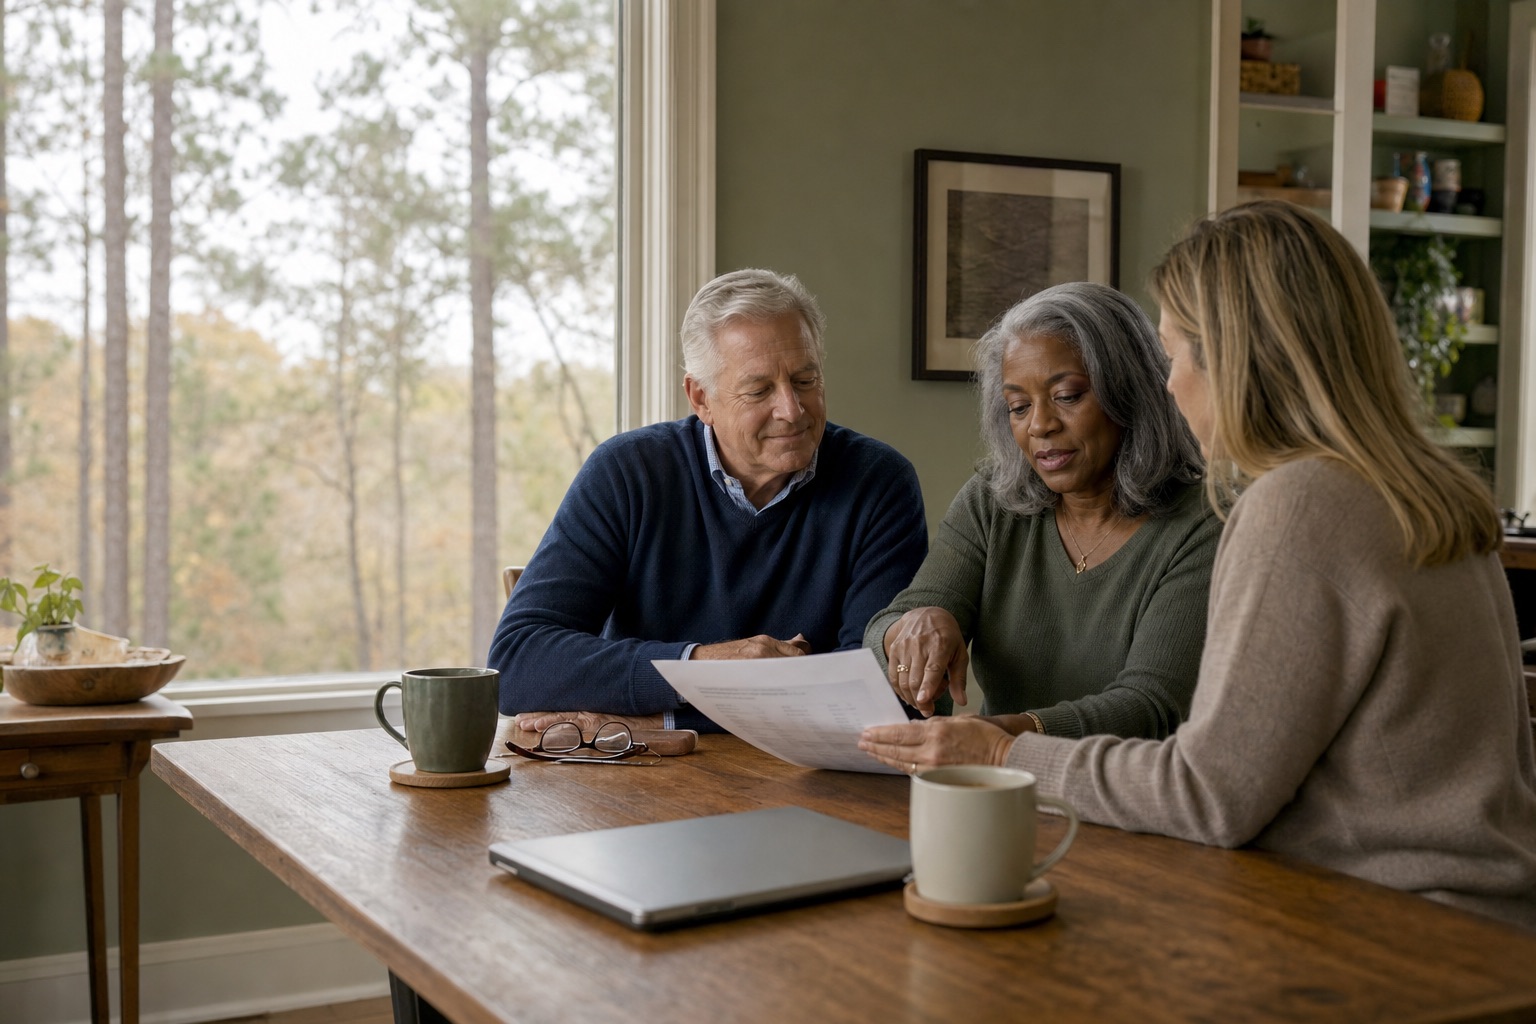
About Varden
Most people drift into retirement. Pilots are given a birthday. That date sets the order of every decision after it: the plan elections, the last year of captain's pay, when Social Security starts and which state you file in.
So we keep the firm small on purpose. Varden is capped at ninety households, and the person who wrote your plan is the one who picks up the phone in the week of your final trip.
“I read the plan documents before I read the statements. The documents decide your options.”Nell Varden, CFP®, founder · fictional person
Who you'll work with
Meetings are booked around your trip calendar, and most happen by video from wherever you are that week.
Nell Varden, CFP®
Founder and planner
Opened Varden in 2015 after twelve years at an Atlanta firm. Her father flew for thirty-one years.
Fictional person
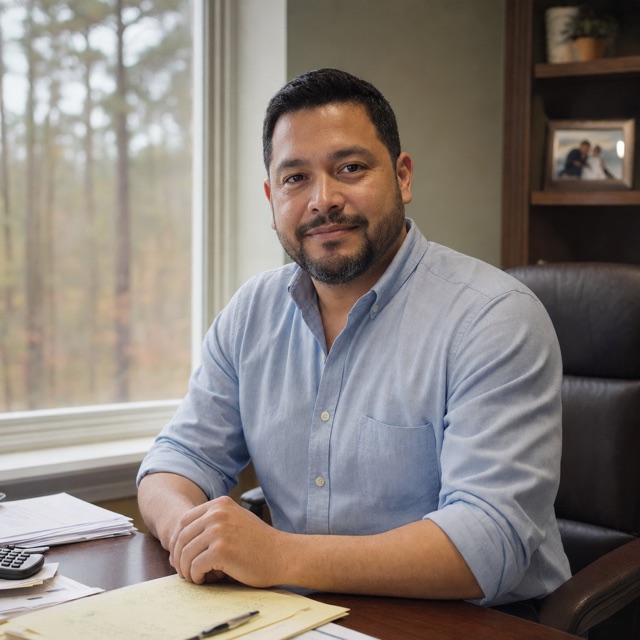
Teo Briggs, EA
Tax and planning
Prepares every client's returns. Six years filing for flight crews in Kentucky before he joined in 2019.
Fictional person
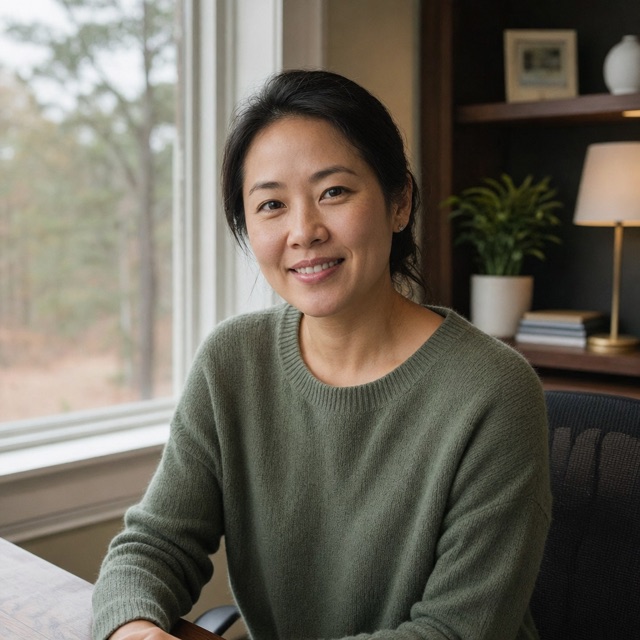
Ana Lisle
Client service manager
Runs the calendar and the paperwork. A form that needs signing mid-trip reaches your phone that afternoon.
Fictional person
What we do
Most of our work happens in the ten years before 65 and the first years after it. Pilots early in their careers we refer to two planners we trust.
Lump sum or monthly, which benefit when, filed together at our table.
What to save, where, and how much tax to pay now rather than later.
When each spouse starts, and what that means for the one who outlives the other.
Federal and state, every spring, by an enrolled agent. Included in the fee.
Accounts in your name at an independent custodian, managed to the written plan.
Benefits, accounts and filings in the right order, one decision at a time.
 Sample image · not the firm's people
“The election packet sat on our counter for a week. Nell had read the plan documents before we met, and we signed it at her table without rushing a single page.”
A retired captain and his wife Sample testimonial · fictional clients
Sample testimonial written by Wealth I/O for a fictional firm; no client said this. A real firm states here: “This statement is a testimonial by a current client of Varden Planning, given on [date]. The client was not paid and received no other compensation for it, and has no material conflict of interest. It may not represent the experience of other clients and is no guarantee of future performance or success.”
How we start
Nothing starts until you have read the plan and agreed to it. If we wouldn't change anything, we'll say so.
45 minutes · phone or video · free
Bring nothing. The only thing we ask for beforehand is your retirement date.
Two meetings, then four pages within 30 days
We read the airline's plan documents, the 401(k), your spouse's benefits and two years of tax returns, then write down which benefit to take when.
Monthly, then quarterly
A call each month for the year before 65, elections signed together, then regular meetings and your tax return each spring.
Notes from Nell
Each note starts with a question someone asked in a meeting, and answers it in the first paragraph.
The short answer depends on three things. The first is what a surviving spouse would need.
What each form decides, and which ones can't be changed later.
For surviving spouses, the order to take the decisions in, and what can wait.
Sample article titles for a fictional firm · general education, not advice for your situation.
A yearly fee on the assets we manage, and nothing else: 0.90% on the first $2 million, 0.60% from $2 million to $5 million and 0.40% above that, with a $7,500 minimum. It is billed each quarter, and every bill shows the calculation. The fee includes the written plan, every meeting and your tax returns.
We take no commissions and sell no insurance or annuities. Sample wording: advisory fees are paid by clients under the schedule in our Form ADV Part 2A, which also describes any other compensation and our conflicts of interest.
Yes, a $7,500 minimum annual fee. Most clients have between $1.5 million and $6 million with us. If you have less, the first call is still free, and we will tell you plainly whether our work would be worth the fee.
No. Money leaves your accounts only on your instruction. We can trade inside them and deduct the agreed fee; withdrawals and transfers need your signature, and the custodian confirms them separately. If Varden closed tomorrow, the accounts would stay exactly where they are.
Yes. Many clients live in other states and fly from other bases. Most meetings are by video, and Teo files in whichever states you owe tax. We ask you to come to Peachtree City once, in the final year, to sign the elections together.
Yes, if a question has gone unanswered. The first call is free and carries no obligation. Some pilots keep their adviser and simply want a second reading of the election packet before they sign it.
A free 45-minute call with Nell, booked on a day off. No paperwork, no obligation.
Start with a conversationOr call Ana at (770) 555-0164, weekdays 8 a.m. to 6 p.m. Eastern